Boring is Beautiful
Why is your investment philosophy so . . . boring?
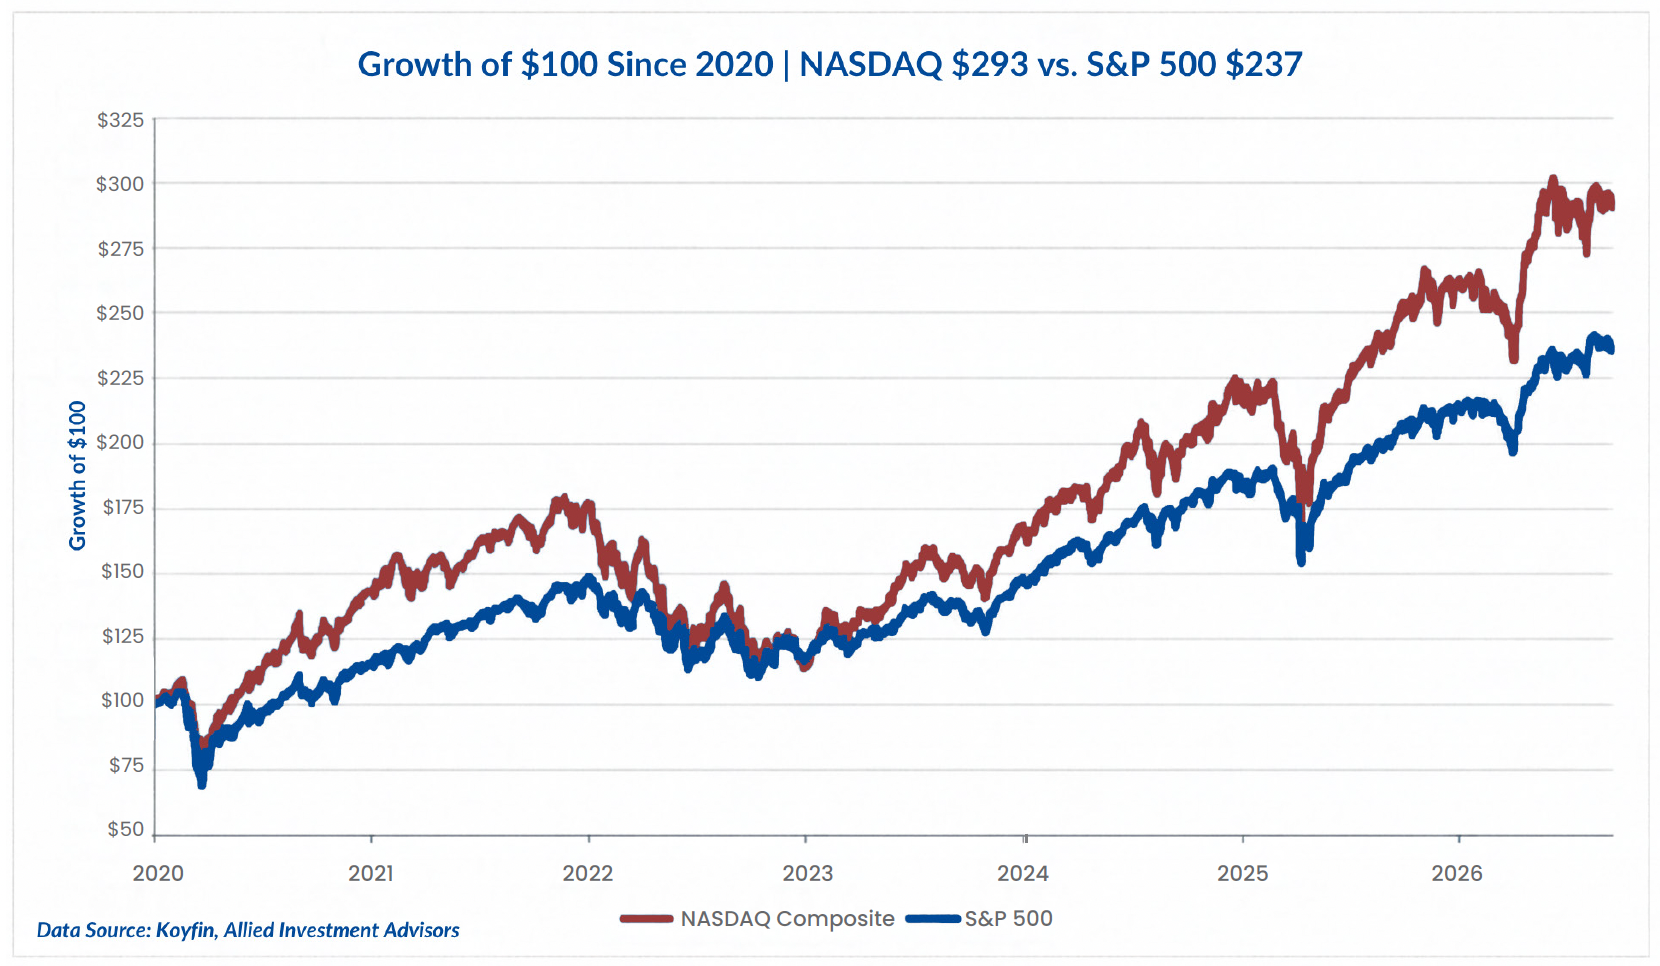
We are often asked why we don’t offer a more aggressive investing option. It’s an understandable question. In recent years, a high-beta, aggressive allocation tilted heavily toward tech names would have worked great. The Nasdaq has easily outpaced the S&P 500 this decade.
Higher risk should, in theory, equal higher return. For younger investors who are decades away from retirement, short-term volatility shouldn't derail their strategy. As long as market turbulence comes with outsized gains, aggressive allocations seem like the obvious choice.
Take technology stocks—the engine of most aggressive portfolios—and compare them to consumer staples, the boring essentials of everyday life. Since 1960, tech stocks have outpaced staples in 36 out of 66 years (55% of the time). Even better, technology has generated a higher simple average annual return of 14.3% compared to 12.8% for staples. Tech investors endured far more volatility, but on the surface, it looks like they were compensated for it.
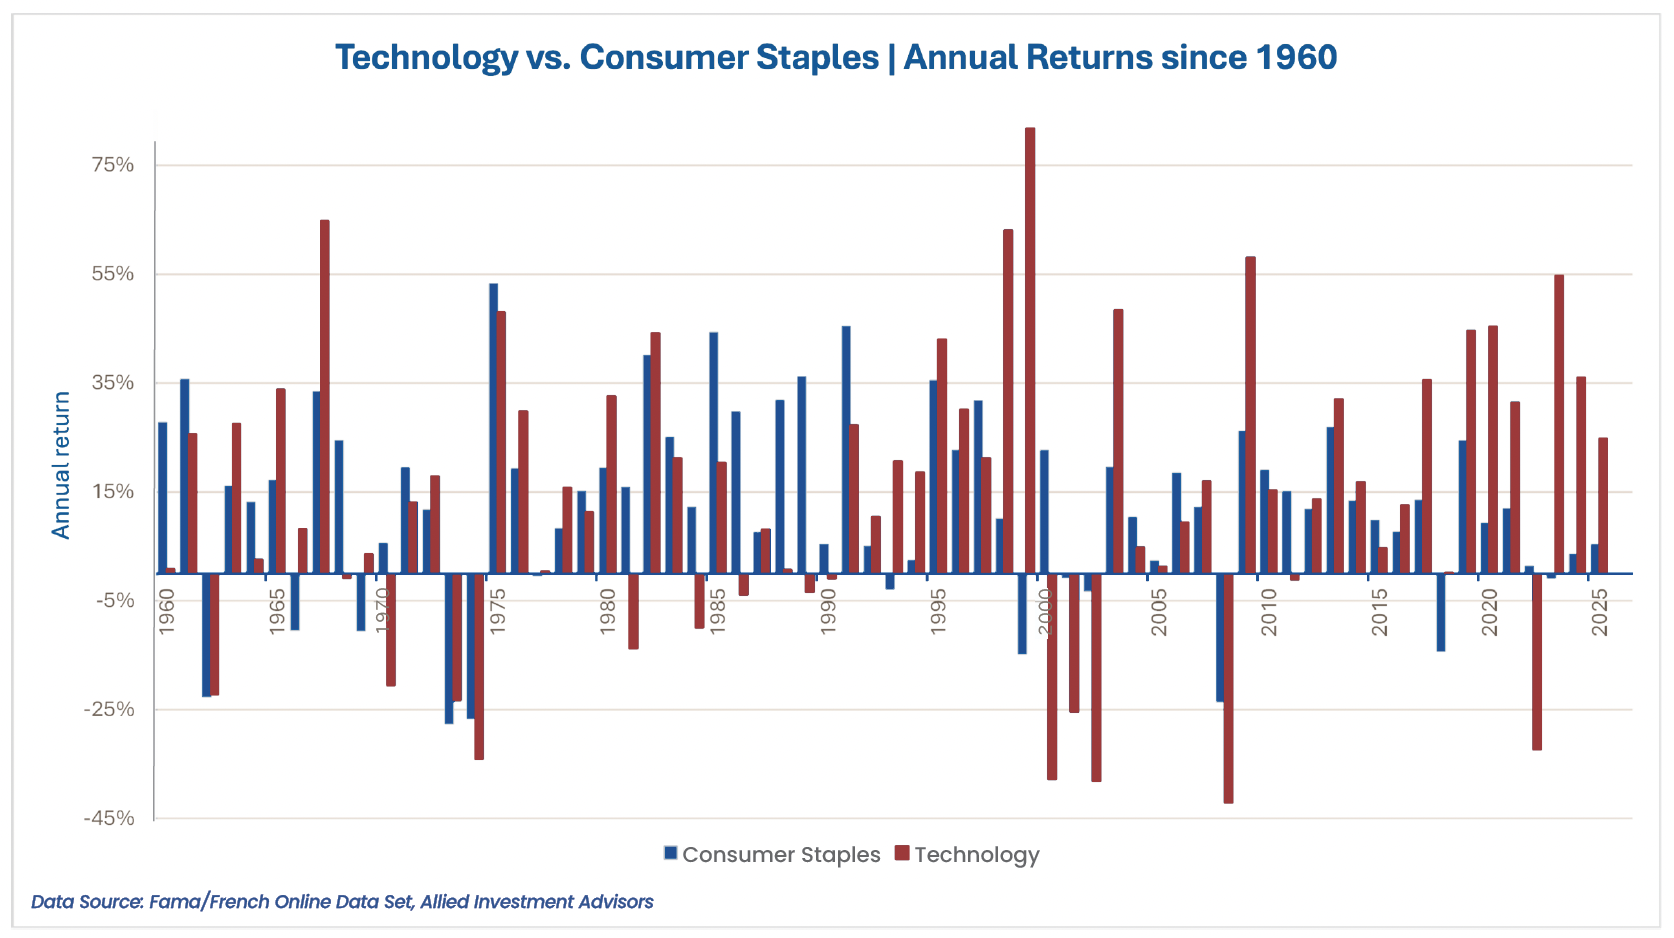
But here is the paradox of market math: despite tech’s higher hit rate, higher average annual return, and undeniable excitement, consumer staples have actually compounded at a higher total rate over the long haul.
How can a lower average return generate more actual wealth? Because simple averages lie; compounding pays you in dollars, not averages. If a stock drops 50% in Year 1 and gains 50% in Year 2, your simple average return is 0%. But your wallet tells a different story: your $100 dropped to $50, then recovered to just $75—a -25% real loss.
This math reveals a fundamental truth: compounding favors the mundane over the magnificent.
Big drawdowns inflict far more mathematical damage than equivalent gains can repair. Because tech suffered far deeper market crashes, it required massive rallies just to break even—allowing the steady, low-volatility returns of staples to compound into a bigger final nest egg.
During the 2008 Great Financial Crisis, tech fell -42%, while staples proved relatively defensive at -25%.
Similarly, in the 2022 bear market, tech dropped -32% while staples actually finished the year up +1.3%.
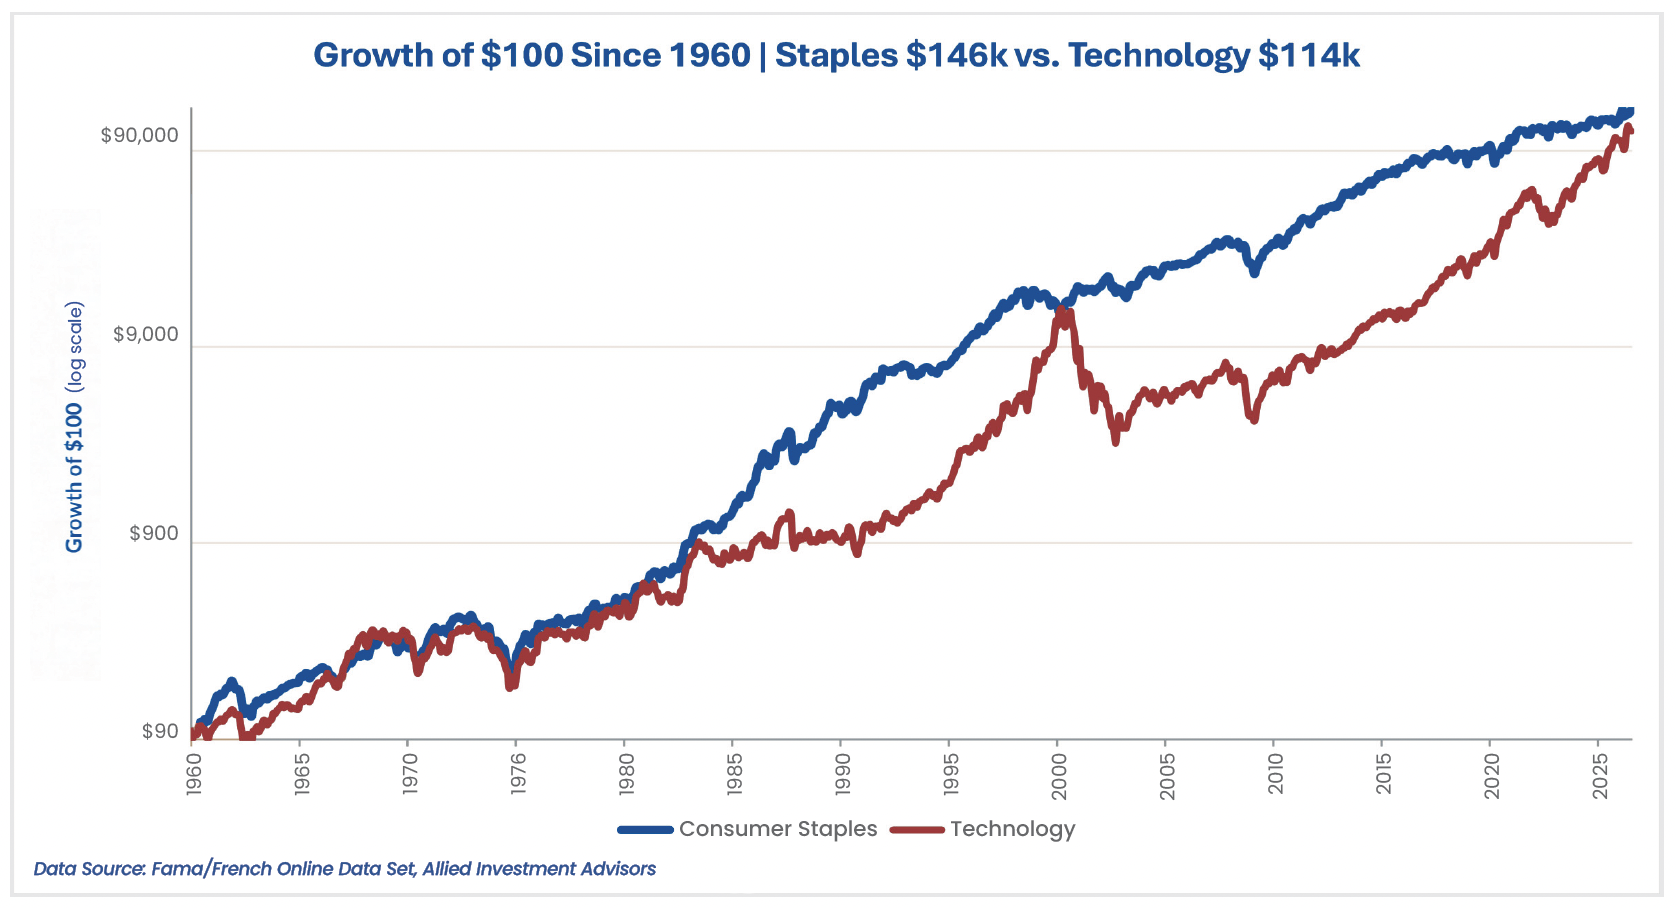
Survivability is a key element of long-term investing. To reach your financial destination, you must survive the journey. While aggressive portfolios dangle high average return numbers, drawdowns and human psychology work against you.
To see how this math impacts real-world behavior, look at Amazon. We all like to imagine buying the stock at its IPO in 1997 and holding a once-in-a-generation winner.
What we conveniently forget is that Amazon stock collapsed -94% in the dot-com crash of 1999–2001. (It also suffered a -65% drawdown in 2008 and a -56% drop in the 2022 bear market, along with numerous other pullbacks). Watching a $100,000 investment shrink to $6,000 in under two years is a psychological blow few investors survive without selling at the bottom. And even if you held on, would you have had the fortitude to wait nearly 10 years (from December 1999 to October 2009) just to break even?
Consumer staples—along with other quality, durable businesses we prioritize in building portfolios for our clients—may lack the glamour of hyper-growth tech stocks. But their drawdowns are often more manageable, helping protect you from impossible decisions when markets turn ugly. Avoiding those panicked moments is central to long-term compounding, and it guides every portfolio decision we make.
Or, as Nobel Laureate Paul Samuelson famously put it: “Investing should be more like watching paint dry or watching grass grow. If you want excitement, take $800 and go to Las Vegas.”
If you have questions about your accounts, have experienced a change in your financial situation or investment objectives, or would like to schedule a complimentary consultation, please contact us at 515-221-1133. We would be glad to discuss how our team can help you navigate the market and pursue your long-term financial goals.
Disclosure: You cannot invest directly in an index, including the S&P 500 Index, the NASDAQ Composite, or the Technology or Consumer Staples Sector Indexes.
The views expressed in this newsletter represent the opinion of DMKC Advisory Services, a Registered Investment Adviser. This material is for informational purposes only. It does not constitute investment advice and is not intended as an endorsement of any specific investment or services. The information provided herein is obtained from sources believed to be reliable, but no representation or warranty is made as to its accuracy or completeness. Investing in equity securities involves risks, including the potential loss of principal. While equities may offer the potential for greater long-term growth than most debt securities, they generally have higher volatility. International investments may involve risk of capital loss from unfavorable fluctuation in currency values, from differences in generally accepted accounting principles, or from economic or political instability in other nations. Past performance is not indicative of future results. Investments are not a deposit of or guaranteed by a bank or any bank affiliate. Please notify DMKC Advisory Services if there have been any changes to your financial situation or investment objectives or if you wish to impose or modify any reasonable restrictions on the management of your accounts through DMKC Advisory Services.
This information is provided for informational purposes only. Therefore, the article above should not serve as the sole determining factor for making investment decisions. The selection of an investment advisor and other investment selections are important decisions that should not be based solely on marketing materials. To the extent that you have any questions regarding the applicability of any specific issue discussed regarding your individual situation, you are encouraged to consult with DMKC Advisory Services. All information, including that used to compile charts, is obtained from sources believed to be reliable, but DMKC does not guarantee its reliability or accuracy.
Different types of investments and/or investment strategies involve varying levels of risk, and there can be no assurance that any specific investment or investment strategy (including investment strategies developed by DMKC will be either suitable or profitable for a client’s or a prospective client’s portfolio and may result in a complete loss of principal. Diversification and asset allocation do not ensure a profit or protect against a loss. All performance results should be considered in light of the market and economic conditions that prevailed at the time those results were generated. Before investing, consider investment objectives, risks, fees and expenses.
Want to be boring with us?
Email boring@dmkc.com to get started!